
 By
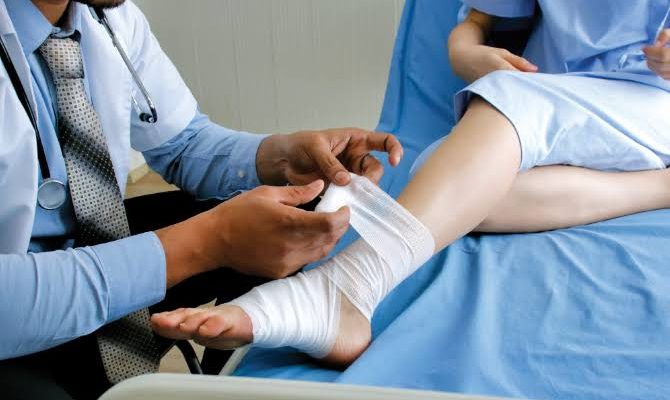
Recovering from a serious injury in Los Angeles, California, can be expensive. Housing costs remain the same even when an accident keeps someone from work, and getting to medical appointments across the city adds another expense during an already difficult time. For an injured person pursuing compensation, those financial demands can become harder to manage when a claim takes longer than expected. The concern is not simply finding money for today. It is about maintaining a stable home, continuing prescribed care, and avoiding legal decisions driven by an immediate cash shortage.
Some plaintiffs therefore consider High Rise Financial legal funding for personal injury lawsuits when their regular income no longer covers essential expenses. Before agreeing to funding, they need to understand what the arrangement will ultimately take from their recovery. That calculation matters most when treatment is ongoing, and the injury claim’s value is still being established through records and negotiations.
Why Cash Pressure Matters
Financial pressure can affect litigation choices. A plaintiff facing an overdue rent payment may accept a quick settlement before medical treatment shows the injury’s full effect. That decision can leave unpaid bills, future care, and lost wages outside the recovery. Funding buys time to compare an offer with documented losses, not your checking account balance.
How Funding Works
Case funding is usually structured as a nonrecourse advance against the expected recovery from a pending claim. Approval usually depends on evidence of fault, medical documentation, available insurance coverage, and possible reductions from prior injuries or disputed liability.
Repayment typically comes from the eventual settlement or judgment, rather than monthly payments. If the case produces no recovery, the written agreement determines whether anything is outstanding, so counsel should explain the exact terms before signing.
How Costs Accumulate
The advertised advance does not show the full cost. A contract can add an origination charge, monthly fees, compounding charges, or a minimum return. Each term changes the payoff balance over time.
Plaintiffs should request written figures for an early settlement, a mid-case settlement, and a later resolution. They should also ask whether fees continue during appeals, delays, or settlement negotiations. Comparing the projected net recovery with other funding sources helps identify the least costly option.
Who Fits This Option
An advance fits a plaintiff with documented hardship and a claim that has a reasonable path to recovery. Missed wages, therapy costs, prescription expenses, child care, and overdue utilities can create immediate pressure.
Need alone does not establish eligibility. The provider also examines liability, treatment progress, coverage limits, and factors that could reduce the final recovery. A plaintiff should discuss whether the requested amount matches essential expenses rather than discretionary spending.
What Attorneys Review
An attorney can explain how an advance affects settlement strategy, liens, fees, and the plaintiff’s final share. Counsel often provides medical records, claim documents, insurance information, and negotiation updates. Those materials help a funding provider assess expected value and timing.
The plaintiff should request a plain payoff example and ask whether the agreement permits early repayment without extra charges. Legal review is especially insightful when the contract uses compounding fees or broad default provisions.
Use Money Carefully
Funding should cover expenses that protect housing, treatment, and basic transportation. Practical examples include rent, groceries, utility bills, prescriptions, and rehabilitation visits. Using an advance for optional purchases increases the payoff without improving the claim.
A simple spending plan can show how much money is necessary each month and prevent an unnecessarily large advance. Plaintiffs should preserve receipts and keep counsel informed if treatment or income changes.
Compare Other Options
Before signing, a plaintiff should compare the advance with available savings, family assistance, payment plans, or traditional credit. A less costly option can preserve more of the eventual recovery.
The comparison should include interest, fees, repayment timing, and the risk of losing access to treatment or housing. If funding remains necessary, the plaintiff should take only the amount required for documented bills and understand the payoff schedule in writing.
Things to Ask First
A written agreement should state the advance, every fee, the payoff method, loss provisions, and the expected net recovery after resolution.
Conclusion
Personal injury funding can stabilize a plaintiff’s finances while treatment and negotiations continue, but the advance changes the claim’s economics. The safest next step is a written review with counsel, followed by payoff projections for several possible resolution dates. Before accepting funds, a plaintiff should compare that total with other ways to pay essential bills. Careful borrowing protects cash flow without surrendering an avoidable share of the final recovery after paying fees and liens.

Comments